Our Podcast Library
Tune in to Gatewood’s podcasts for financial insights from our experienced team.
Listen Now →
Physicians and practice owners often max out a 401(k) early in the year and find there is nowhere else to put pre-tax dollars. A cash balance plan sits alongside the 401(k) and raises the annual ceiling substantially.
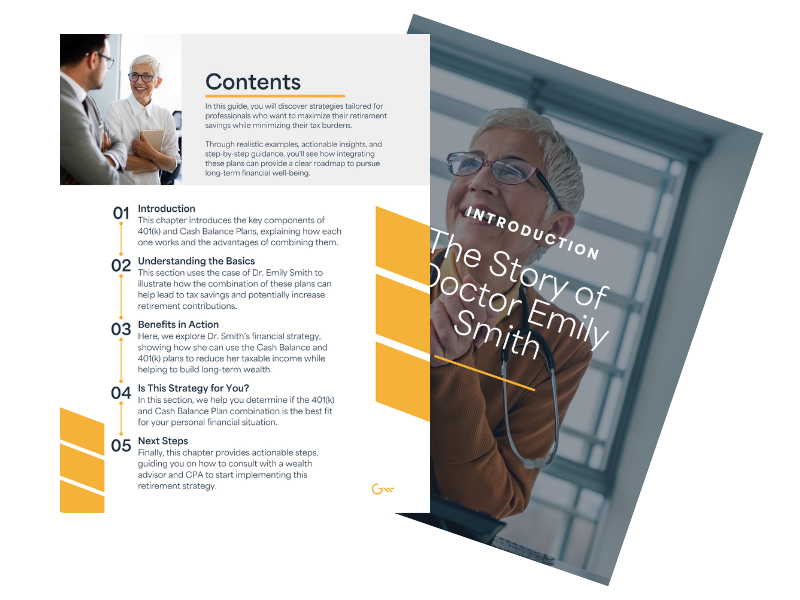
This guide explains how the two plans work together, what the combination looks like for a physician earning $600,000, who needs to be involved to set one up, and the trade-offs worth weighing first. Download your free copy below.
A cash balance plan is a type of defined benefit plan that lets a business owner contribute far more per year than a 401(k) allows on its own. Contributions are set by an actuary based on age and income, which is why the ceiling rises sharply for owners over 40. Pairing one with an existing 401(k) is often called a combination plan.
The guide covers: