Everyone Wants to Talk About Returns. Almost No One Asks the Better Question.
Walk into most financial reviews and the first question is usually some version of: “How are my investments doing?”
It’s a natural place to start. Returns are visible, measurable, and emotionally charged. They are also, in most plans, far less important than the question almost no one asks: “How is my cash flow holding up?”
Cash flow is the current that runs underneath everything else in a financial plan. Spending, saving, taxes, debt service, retirement income, charitable giving — every one of them moves through it. And yet, in family after family, it’s the part of the plan that gets the least dedicated attention.
That gap is the difference between a plan that looks good on a statement and one that actually holds up over time.
Wealthy on Paper, Fragile in Practice
Here’s what we see, again and again.
A successful family — solid income, meaningful investment balances, an advisor they like — sits down to review their plan. The portfolio looks healthy. The retirement projection looks reasonable. But when we ask basic cash flow questions, the answers get fuzzy:
- How much cash do you actually need on hand for the next 12–24 months?
- Where is that cash held, and is it positioned to address near-term spending?
- If markets dropped 30% tomorrow, would you have to sell investments to cover expenses?
- How much of your monthly income is being directed toward goals — versus quietly absorbed by lifestyle creep?
These aren’t trick questions. They’re the foundation of a working plan. But they often go unanswered because cash flow doesn’t get the same airtime as investment performance.
The result is a household that looks wealthy on paper but is more fragile in practice than anyone realizes.
Why Cash Flow Quietly Slips Through the Cracks
There are three reasons cash flow gets skipped in most planning conversations.
1. The industry rewards talking about returns.
Performance is exciting. It’s the part of finance that fits on a chart and dominates the headlines. Cash flow is operational — and operational topics rarely make for compelling pitches.
2. People assume “I have a budget” equals “I have a cash flow plan.”
They aren’t the same thing. A budget tracks where dollars went last month. A cash flow plan is forward-looking and structural — it positions where dollars need to be, and when, to support a multi-decade financial picture.
3. Cash flow gaps don’t show up until pressure does.
When markets are calm and incomes are steady, the cracks don’t show. Then comes a downturn, a business sale, a job change, a parent’s care need, or the first year of retirement — and the gap becomes visible at exactly the moment it’s hardest to fix.
This is the planning gap most firms stop at. They name it. They say cash flow matters. They don’t show you what to actually do about it. </span></p>
Two Households, Same $3 Million, Very Different Retirements
Consider two households. Each has $3 million in invested assets and $15,000 a month in expected retirement spending. Same numbers on paper. Very different outcomes.
Household A: “We’ll Just Draw What We Need”
- Keep about two months of expenses in checking
- Hold the rest in equities and a small, fixed income allocation
- Plan to draw from investments as needs come up
Then markets fall 25% in their second year of retirement. With no cash buffer in place, they’re forced to sell equities at a loss to cover spending. Each sale locks in the decline. This is sequence-of-returns risk, and the research is consistent: poor returns in the first decade of retirement, combined with ongoing withdrawals, can permanently shorten how long a portfolio lasts.
Household B: A Plan That’s Already Positioned for the Drop
- Two years of expected spending — roughly $360,000 — held in liquid, conservative cash alternatives
- Five to eight additional years of spending in high-quality fixed income
- The remainder positioned for a long-term time horizon in equities
When markets fall, they spend from cash. Equities are left alone to recover. They never have to sell low to fund the grocery bill.
Same portfolio. Same goals. Two very different outcomes — driven entirely by cash flow structure.
What to Hold Onto
- Cash flow — not investment returns — is most often what determines whether a plan holds up under stress.
- A budget is backward-looking. A cash flow plan is forward-looking and structural.
- Sequence-of-returns risk in early retirement is one of the most damaging — and most preventable — cash flow failures.
- Cash flow planning is a coordination problem. It lives across investments, taxes, debt, insurance, and goals at the same time.
How Gatewood Builds Cash Flow Into the Plan, Not Around It
Cash flow is one of the areas where our structure shows up most clearly. Two of our differentiators are built specifically to address it: Cash Hubs and Fortress Gatewood.
Cash Hubs: Cash With a Job to Do
Cash Hubs are deliberately structured cash positions inside your overall plan. Rather than letting cash sit in a single checking account by default, we work with you to create defined hubs — operating cash for monthly needs, reserve cash for short-term obligations, and opportunity cash for goals on the horizon (a business move, a property, a meaningful gift, a planned care expense).
Each hub has a purpose, a target balance, and a refill rule. That structure does two things at once: it keeps cash positioned where it’s appropriate for its time horizon, and it helps reduce the need to pull investment dollars to cover gaps that should have been planned for. The amount of cash held in our cash hubs at any given time is directed by the Gatewood Investment Committee. They thoughtfully prune the portfolio when the market is doing well and spend the hubs when the market is down.
Fortress Gatewood: Three Rings of Breathing Room
Fortress Gatewood extends that thinking into the investment portfolio itself. The approach builds three concentric rings around your assets:
- Ring 1 — Immediate Preservation: approximately two years of expected spending, held in liquid cash alternatives.
- Ring 2 — Mid-Term Safeguard: five to eight years of planned spending, invested in high-quality fixed income.
- Ring 3 — Long-Term Growth: designed for a 7–10+ year time horizon, invested in globally diversified equities.
The mechanism matters. With two years of cash and five to eight years of bonds positioned ahead of equities, our clients are not forced to sell equities during a down market to fund their lives. That breathing room is designed to give a portfolio time to recover without emotion driving the decision.
One Plan, Coordinated by One Team
This is what we mean when we talk about Firm-to-Family®. Cash flow planning isn’t a side service — it’s coordinated across our investment, tax, financial planning, estate, and insurance offerings so the plan moves as one. A change in one area doesn’t quietly create a gap in another. That’s the difference between knowing cash flow matters and being structured for it.
Let’s Look at Your Cash Flow as Its Own Conversation
If you’ve never had your cash flow examined as its own line of work — separate from your investments, your taxes, or your spending — that’s a reasonable first conversation to have. We can walk through what your cash flow structure looks like today, where the gaps may be, and how each part of your plan is (or isn’t) coordinated around it.
Important Disclosures:
Content in this material is for general information only and not intended to provide specific advice or recommendations for any individual. Gatewood Wealth Solutions and LPL Financial do not provide legal or tax advice or services.
All investing involves risk including loss of principal. No strategy assures success or protects against loss.
This information is not intended to be a substitute for specific individualized tax or legal advice. We suggest that you discuss your specific situation with a qualified tax or legal advisor.
If you’re in your 20s or 30s, money can feel like a language you were never taught.
You’re earning more than you did before. You might have student loans. You have access to credit cards. Retirement accounts show up in onboarding paperwork. People talk about investing, buying homes, retiring early
You don’t know where to start.
You’re not sure who to talk to.
You don’t even know what questions you’re supposed to be asking.
All the while, you’re expected to “figure it out.”
Why It Feels So Overwhelming
For many people, personal financial education in school was limited or nonexistent. Unless you studied finance in college or had a parent who walked you through budgeting, you’re learning as you go. Most young adults are making real & impactful financial decisions for the first time without much context for how those decisions connect.
At the same time, the system makes spending remarkably easy. Credit cards are marketed as lifestyle tools. Student loans are framed as necessary stepping stones. Buy-now-pay-later options show up at checkout with a single click. None of these are automatically harmful, but without structure they can begin shaping your financial life before you’ve had the chance to think strategically about it.
Then you look ahead. Headlines talk about housing prices, retirement targets and market volatility. Buying a home can feel daunting. Retirement feels too distant. The space between where you are and where you think you should be starts to feel wide.
And here’s the difficult part — ignoring it doesn’t really work. Your 20s and 30s are when credit history is built, spending habits solidify and retirement accounts quietly begin to matter. This stage offers a rare advantage: time. But most people are trying to learn the rules while already playing the game.
That’s often where anxiety begins.
What Are Good Financial Habits in Your 20s and 30s?
Building good financial habits in your 20s and 30s is going to feel impossible if you’re worried about mastering everything at once.
If we can take a step back from the laundry list of worries, we can focus on the key ingredients to healthy habits: building stability, creating visibility into your cash flow and beginning to invest consistently while you learn.
Our big picture is gaining confidence, clarity and direction, not achieving perfection.
Step One: Create Stability Before Strategy
Before investing more, before optimizing taxes, before trying to “catch up,” your financial stability is the priority.
How can you work toward financial stability? Start by honing in on the founding pillars. The very first step always begins with understanding what’s coming in, and what’s going out.
Understand your fixed monthly expenses
Start by listing out:
- The sources of income you can rely on with certainty. Not commissions and bonuses, but the amount that you are guaranteed in your recurring payments from your employer.
- The expenses you are obligated to pay. These are things that you cannot live without like utilities, food, or things you’ll be penalized for not paying like, rent, student loans, and car payments.
- The expenses you can expect to pay. These are things you could live without but are likely to spend at some point like new clothing, travel, subscription services, and dining expenses.
Comparing these side by side will give you a better idea of what’s left over, what needs to be cut, and what can wait.
Build a starter emergency fund
We recommend 3-6 months of emergency reserves. These reserves should cover your normal living expenses if you were to lose your primary source of income for whatever reason.
For those struggling to pay the bills, this will seem like a mountain at first. That’s okay. It won’t happen overnight, but once you get there, you’re free to take more risks when you need to, knowing you have a cushion you can rely on.
Avoid long-term credit card balances
Knowing what your monthly expenses are is key to planning ahead. Keeping your credit cards at or below a balance that can be paid in full each month is critical. Our goal is to accumulate wealth, not debt. For some this is easier said than done, and that’s when financial coaching can be extremely useful.
This isn’t glamorous and it’s not something you can do just once. You’ll need to revisit this from time to time, at least once every few months, and track your progress. But in time, you’ll find that the clarity you’ve gained outpaces the fear that not knowing created.
When you have cash reserves and awareness of your spending, stress decreases and you’re free to look further ahead with more confidence.
Step Two: Start Participating — Even If It’s Small
If your employer offers a retirement plan like a 401(k), this is often one of the easiest places to begin.
A 401(k) is simply an account that lets you contribute money directly from your paycheck before it hits your bank account. That money is then invested and allowed to seek growth over time.
You don’t need to be an expert to start. You don’t need to wait until everything else in your financial life feels perfect. Once you understand roughly what your monthly income and expenses look like, you can begin contributing an amount that feels manageable.
Even small percentages matter early because time is working in your favor. The earlier you start, the more years your contributions have the opportunity to compound.
Also, many employer-sponsored plans offer access to an advisor at no additional cost to employees. That person can help you:
- Understand how the plan works
- Review how much you’re currently contributing
- Explain whether your employer offers a match
- Walk through how your money is invested
The “match” is especially important. Some employers contribute additional money when you contribute to your 401(k), up to a certain percentage. If that’s available to you, it’s worth understanding how it works.
When you log into your retirement account, you’ll see your contributions invested in funds. Those funds are typically diversified across many companies or bonds. You are not expected to know how to build that from scratch on day one. Learning what those allocations mean over time is part of developing financial literacy.
It’s okay if no one ever explained this before. Most people are figuring it out for the first time in their 20s and 30s.
The goal here isn’t perfection. It’s participation.
Step Three: Understand the Flow of Your Money
This is where many young professionals start to feel stuck. For most people, money follows a simple pattern: income comes in, bills get paid and whatever is left over may or may not go toward savings. It isn’t intentional — it’s just the default.
A healthier approach shifts the order slightly. Instead of saving what happens to remain, you decide in advance what percentage of your income goes toward savings or investing. Then you build your spending around what’s left.
That small change creates structure. Even increasing your savings rate by 1% each time you receive a raise can gradually improve your long-term flexibility without dramatically changing your lifestyle.
The goal isn’t restriction. It’s clarity about where your money is going and why.
Student Loans, Credit Cards and “Necessary Evil” Debt
Debt is often part of this stage of life. Student loans may have helped increase your earning potential. Credit cards can help establish credit history. A car loan may simply be the way you get to work each day.
The issue usually isn’t the presence of debt. It’s whether the debt is intentional or automatic.
High-interest balances that roll from month to month can quietly create financial drag. When you understand your interest rates, repayment terms and payoff options, you move from reacting to debt to managing it. That shift alone can change how in control you feel.
Buying a Home and Retiring Feel Far Away
For many people, buying a home or retiring feels distant. And in your 20s or early 30s, it probably is.
That’s okay.
Homeownership and retirement planning don’t require immediate perfection. They require steady groundwork. Consistent saving habits, gradually increasing retirement contributions, manageable debt levels and improving financial literacy all build toward those milestones over time.
You don’t have to solve the end goal today. You just have to keep building toward it.
The Real Challenge: Decisions Made in Isolation
One of the biggest sources of stress isn’t income. It’s fragmentation.
Most financial decisions happen one at a time. You open a credit card. You sign up for workplace benefits. You refinance a loan. You begin investing. Each decision may make sense on its own, but rarely does someone explain how they connect.
Investment management affects long-term accumulation. Cash management influences flexibility and risk tolerance. Financial planning ties your goals to realistic timelines. When those areas aren’t coordinated, money can feel scattered and reactive. When they work together, the picture becomes clearer.
Confidence Comes From Seeing the Full Picture
Confidence doesn’t come from knowing everything. It comes from understanding where you stand today, what deserves attention now, what can wait and who to ask when something feels unclear.
In your 20s and 30s, financial decisions often feel isolated. You open a retirement account. You take on student loans. You start investing. You build credit. Each step seems separate, but they’re connected.
How you manage cash affects how you invest. How you invest influences future flexibility. How you plan determines what you’re ultimately working toward.
You don’t need to master the entire financial system at this stage. You need structure — a way to see how investment management, financial planning and cash management fit together so your decisions support each other instead of competing.
That’s why Understanding the Full Picture matters early, not just later in life. Through our Firm-to-Family® approach, you’re supported by a coordinated team that evaluates your situation collectively rather than in pieces. If you’re ready to move from confusion to clarity, let’s start a conversation.
Important Disclosures:
Content in this material is for general information only and not intended to provide specific advice or recommendations for any individual. Gatewood Wealth Solutions and LPL Financial do not provide legal or tax advice or services.
All investing involves risk including loss of principal. No strategy assures success or protects against loss.
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.
This information is not intended to be a substitute for specific individualized tax or legal advice. We suggest that you discuss your specific situation with a qualified tax or legal advisor.
When Decisions Affect More Than Just You
Most financial decisions begin with a straightforward question:
Can I afford this?
But when others depend on you—your family, employees, or business partners—that question quickly becomes incomplete.
For business owners and families alike, financial decisions rarely exist in isolation. Choices about income, reinvestment, compensation, or taxes tend to ripple outward. They affect household stability, payroll consistency, and the ability to respond when conditions change. When those ripple effects aren’t fully understood, even well-intentioned decisions can introduce unnecessary stress.
Planning with others in mind requires more than optimization. It requires understanding how tax strategy, cash flow, and liquidity interact in real life—not just on paper.
Why are tax and cash flow decisions more complex when others depend on you?
At their core, tax and cash flow decisions are about timing and access. When does money come in? When does it go out? And when do tax obligations intersect with both?
When decisions affect more than one person—a spouse, children, employees, or partners—planning must balance efficiency with predictability and flexibility. A strategy that minimizes taxes but restricts access to cash can feel very different when payroll is due, tuition bills are approaching, or a family member needs support.
In those moments, the “right” decision isn’t always the one that looks best on a tax return. It’s the one that holds up operationally and emotionally when pressure is applied.
Growth Requires Cash—Not Just Profitability
As a CFO of a fast-growing financial services firm, I’ve learned that profitability alone does not guarantee stability. A business can be profitable on paper and still be under real financial pressure.
I also find that many executives underestimate—or misunderstand—the cash conversion process. Growth consumes cash long before it produces it. New hires must be paid before revenue ramps. Technology investments are made upfront. Office expansion, benefits, and rising operating costs all require liquidity well before earnings reflect the growth.
Without sufficient cash, even healthy growth can introduce strain.
That’s why many of the key performance indicators we track internally focus on cash and solvency, not just revenue or margins. One of the simplest—and most telling—is cash on hand relative to total expenses.
At Gatewood, we aim to maintain approximately 90 days of cash on hand. This buffer allows us to remain steady during volatile markets, uneven revenue cycles, or unexpected disruptions—without forcing reactive decisions that affect our team or our clients.
For executive and business-owner clients, this is best understood as the business equivalent of an emergency fund.
The same principle applies at the household level. For families in the accumulation stage, we typically recommend maintaining six to twelve months of cash reserves. This isn’t about pessimism; it’s about optionality. Cash provides flexibility, preserves long-term plans, and reduces the likelihood of being forced into decisions at the wrong time.
Why These Decisions Carry More Weight Than They Appear
We often see families and business owners make decisions that are technically sound but practically stressful.
A business reinvests aggressively, confident in long-term growth, only to feel pressure when a large tax bill arrives during a low-cash period. A family defers income to reduce taxes, then realizes they’ve limited their ability to respond to unexpected expenses. On paper, each decision made sense. In practice, the strain shows up elsewhere.
When others depend on you, the margin for error narrows—not because mistakes are unforgivable, but because the consequences are shared.
Where Families and Owners Commonly Feel the Strain
Tax and cash flow challenges rarely stem from a lack of income alone. More often, they arise from timing mismatches and structural blind spots.
These challenges tend to surface during periods of transition: business growth or contraction, compensation changes, ownership transitions, or retirement planning. In those moments, cash needs and tax obligations can collide in ways that feel surprising—even to those who have managed finances responsibly for years.
For families, this can disrupt household stability. For business owners, it can create pressure that extends to employees and operations.
The Tradeoff Between Tax Efficiency and Liquidity
Every tax decision affects cash flow, and every cash decision carries tax consequences. The challenge is that the “best” decision depends on context.
Reducing taxable income may improve efficiency but limit near-term liquidity. Retaining earnings in a business may help manage taxes but increase operational risk. Drawing income to create stability may feel prudent, even if it increases tax exposure.
There is rarely a universally correct answer. The right decision depends on who is impacted, how predictable cash needs are, and how much flexibility the situation requires.
How Coordinated Planning Helps Decisions Hold Up in Real Life
Balancing tax efficiency and cash flow isn’t just an exercise in math. It requires perspective, coordination, and an understanding that circumstances will change.
While forecasting and modeling are important, no plan remains static. Markets shift. Businesses evolve. Family needs change—often in ways that can’t be predicted in advance. For that reason, effective planning cannot be a one-time event.
Many families and business owners don’t feel equipped to continually evaluate these tradeoffs on their own—and they shouldn’t have to. A coordinated, ongoing planning approach, such as Gatewood’s Firm-to-Family® model, helps by:
- Translating tax strategies into real-world cash flow implications
- Identifying pressure points before they become urgent
- Stress-testing decisions against scenarios like income changes, market volatility, or unexpected expenses
- Aligning financial decisions with the people and responsibilities those decisions support
- Adjusting strategies as life, business, and responsibilities evolve over time
This continuity ensures decisions remain aligned with reality—not just with assumptions made months or years earlier.
Asking Better Questions Before Making Major Decisions
When decisions affect others, clarity often begins by reframing the conversation.
Instead of focusing solely on optimization, families and business owners benefit from asking how a decision will function under stress, not just during calm periods:
- If revenue declines or expenses rise unexpectedly, will this decision still allow the business to comfortably cover payroll, taxes, and personal obligations?
- Does a tax-efficient strategy preserve enough liquidity to handle healthcare costs, family support, or unplanned needs?
- Would this choice add stress during a market downturn or economic slowdown?
- Does the timing align with other life transitions, such as retirement, ownership changes, or growing family responsibilities?
- If circumstances change, is this strategy flexible—or difficult to unwind?
These questions surface tradeoffs that aren’t always obvious on paper and encourage decisions that support real people—not just financial models.
When Tax and Cash Flow Planning Matter Most
This balance becomes especially important during periods of change—business growth or contraction, ownership transitions, major investments, or times when families and employees need added stability.
In these moments, understanding the full picture can prevent avoidable strain and help decisions hold up over time.
The Firm-to-Family® Difference
At Gatewood, holistic planning starts with a simple recognition: financial decisions rarely affect just one person.
Our Firm-to-Family® approach integrates tax planning, cash flow, investments, and long-term strategy so decisions are evaluated in the context of the people and responsibilities connected to them. Rather than viewing each decision in isolation, we look at how strategies interact across life stages, business cycles, and periods of change.
The goal is straightforward: help families and business owners make financial decisions that hold up—not just on paper, but in real life—for the people who rely on them.
Learn how our Firm-to-Family® approach can strengthen your financial plan.
Important Disclosures
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.
This information is not intended to be a substitute for individualized tax advice. We suggest that you discuss your specific tax situation with a qualified tax advisor
What if the money sitting in your savings account—the cash you think isn’t “working hard enough”—is actually your most powerful wealth-building tool?
When Everything Changed for the Johnsons
Meet David and Sarah Johnson. Successful professionals. Smart investors. They’d been told by their previous advisor to “put every dollar to work” and minimize cash holdings. When the 2008 market crash hit, they watched their retirement accounts plummet just as David lost his job.
With no meaningful cash reserves, they faced an impossible choice: liquidate investments at their lowest point to pay bills, or rack up debt on a line of credit their advisor had recommended as a “cash alternative.”
They chose the line of credit. Big mistake.
By the time David found work eighteen months later, they’d accumulated $75,000 in debt at variable interest rates. Worse, they’d missed the entire market recovery because every spare dollar went to paying down that debt instead of buying investments at rock-bottom prices.
The Johnsons learned a hard lesson:
It’s not what you make on cash that matters, but what cash allows you to make on everything else.
The Gatewood Cash Philosophy: Savings vs. Investments
At Gatewood Wealth Solutions, we make a crucial distinction that most advisors ignore. Savings are inherently less risky, and the funds are liquid. Investments are 100% at risk 100% of the time. This isn’t just semantics. It’s the foundation of building enduring wealth with purpose.
Many advisors will tell you to “put your cash to work” in something “safe.”
Here’s the truth: there is no such thing as a safe investment. All investments carry the risk of loss. When someone says they want their cash to “make money,” they’re confusing the purpose of cash with the purpose of investments.
Cash serves two critical functions in wealth building:
- To avoid liquidating investments at the wrong time
- To seize opportunities
Notice both purposes matter most when investment values decline. That’s not coincidence—it’s strategy.
What This Means: The Mathematics of Opportunity
Let’s examine what happened to Jane, a hypothetical 65-year-old retiree with a $2 million IRA, planning to withdraw $140,000 annually (7% of her initial balance). ¹
Scenario 1: No Cash Strategy
Jane withdraws systematically from her S&P 500 investments regardless of market performance during the period 1973-1988.
Result at age 80: $1,442,897.
Scenario 2: Strategic Cash Reserve
Jane uses cash reserves during the four down market years, preserving her investments when values are depressed.
Result at age 80: $3,763,052.
The difference? A staggering $2.3 million.
Here’s what makes this remarkable: the investment performance was identical in both scenarios. The only difference was having $478,146 in cash to tap during down years.
Even if Jane earned absolutely nothing on that cash, her outcome was dramatically better.
Why This Matters: The Line of Credit Trap
Most advisors today recommend lines of credit as “cash alternatives.” They’ll say, “Why keep cash earning nothing when you can access credit when needed?”
This approach adds both cost and risk to your financial plan.
The Hidden Costs:
- Interest payments on borrowed funds
- Variable rates that can spike unexpectedly
- Loan payments that prevent you from buying investments when they’re cheapest
- Credit limits that can be reduced exactly when you need them most
The Real Risk: Lines of credit turn temporary market downturns into permanent wealth destruction. Instead of having cash to weather storms and capture opportunities, you’re paying interest and missing recoveries.
At Gatewood, we believe wealth is personal. Your cash needs are unique to your situation, your goals, and your confidence.
The Gatewood Cash Formula
Our process-driven approach calculates your optimal cash position based on your life stage:
Accumulation Phase:
3-6 months of expenses for emergencies. This protects your systematic investing strategy (dollar-cost averaging) from being derailed by life’s unexpected moments.
Approaching Retirement:
Gradual accumulation toward your 24-month target, ensuring you enter retirement with adequate liquidity.
Distribution Phase:
24 months of your income shortfall after guaranteed sources like Social Security and pensions. This creates a buffer that allows your investments to recover from market downturns.
An Analogy That Clicks
Think of cash like the foundation of a house.
You don’t build a foundation to be beautiful or to generate income. You build it to support everything else. The stronger your foundation, the taller and more ambitious your structure can be.
Cash works the same way in your financial plan. It’s not there to generate returns—it’s there to support higher returns in your investment portfolio by giving you the confidence to take appropriate risks and the flexibility to act when opportunities arise.
Would you rather have a beautiful foundation that crumbles under pressure, or a solid foundation that allows you to build wealth that endures?
When Lines of Credit Do Make Sense
To be clear, we’re not opposed to all forms of credit. Securities-backed lines of credit can serve a strategic purpose in specific, short-term situations where cash flow timing creates temporary gaps.
For example, if you’re buying a new home before your current one sells, a securities-backed line provides bridge financing without forcing you to liquidate investments or miss out on your dream property.
Similarly, if you’re expecting a substantial bonus, stock options vest, or you’re closing on the sale of a business within a few months, using credit to bridge that gap can make perfect sense. The key distinction is timing and certainty.
These are situations where you have reasonable confidence that cash will follow in a relatively short period—typically 3-6 months. What we caution against is using lines of credit as a permanent cash substitute or relying on them for unpredictable expenses where the repayment timeline is uncertain.
The difference between strategic short-term leverage and dangerous cash replacement is the difference between a useful tool and a wealth destroyer.
Other circumstances where securities-backed lines of credit might make sense include:
- Tax payment timing (when you know a refund is coming)
- Seasonal business cash flow needs with predictable revenue cycles
- Taking advantage of a time-sensitive investment opportunity when a planned asset sale is imminent
- Emergency situations where immediate access is needed and cash reserves are being replenished through planned distributions
The Gatewood Difference
While other advisors chase yield on every dollar, we focus on purpose. We keep your priorities the priority.
Our relationship-driven approach means we understand your unique situation, your concerns about market volatility, and your need for confidence in uncertain times. The true value of planning is the confidence it creates.
We’re not product-driven—we’re process-driven. We don’t sell you investments. We guide you through building enduring wealth with purpose so you can have confidence for life’s key moments.
With expertise and care, our team monitors your cash position throughout different market cycles, adjusting as opportunities arise or as your circumstances change.
What Happens Next
During strong markets, we deploy cash strategically at lower valuations. As markets reach new highs, we begin raising cash by taking profits in specific asset classes. During weak markets, we may redeploy cash at lower valuations or spend down reserves to give investments time to recover.
This isn’t market timing—it’s strategic cash management that puts you in control of your financial destiny.
Your Next Step
If you’re tired of advisors treating every dollar the same, if you want a wealth strategy built around your unique situation and goals, if you’re ready to discover how proper cash management can supercharge your investment returns, we should talk.
Don’t let another market cycle catch you unprepared. Don’t rely on debt to fund opportunities or weather storms.
Ready to discover what your cash can really do for your wealth?
Schedule a conversation with our team to learn how Gatewood’s cash philosophy can transform your financial confidence. Because at Gatewood Wealth Solutions, we understand that wealth with purpose starts with understanding what each dollar should accomplish.
Remember: It’s not what you make on cash that matters, but what cash allows you to make on everything else.
References
(1) Hypothetical example for illustrative purposes only. Beginning value $2,000,000 in IRA; S&P 500 historical return during 1973-1987, including dividends; $140,000 withdrawal each year: $0 withdrawal in years after a negative return except for required minimum distribution. These numbers do not reflect fees and charges associated with an actual investment. Historical S&P 500 returns from Bloomberg. The S & P 500 Index is a list of securities frequently used as a measure of U.S. Stock Market performance. Required minimum distributions from the IRA under Federal Tax Law. Source of diagrams from Northwestern Mutual’s brochure, “Down Markets Matter”, 67-0788 (0715).
(2) Investopedia – A required minimum distribution (RMD) is the amount that traditional, SEP or SIMPLE IRA owners and qualified plan participants must begin distributing from their retirement accounts by April 1 following the year they reach age 70.5. RMD amounts must then be distributed each subsequent year based on the current RMD distribution calculation amounts. http://www.investopedia.com/terms/r/requiredminimumdistribution.asp#ixzz4nzGcn0T4
(3) The primary purpose of permanent life insurance is to provide a death benefit. Using cash values to supplement your retirement income will reduce the benefit and may affect other aspects of your life insurance plan. Accessing the cash values through policy loans, surrenders of dividend values, or cash withdrawals will or could; reduce death benefit; necessitate greater outlay than anticipated; or result in an unexpected taxable event. Assumes a non-Modified Endowment Contract (MEC).
(4) Dollar-cost averaging (DCA) is an investment technique of buying a fixed dollar amount of a particular investment on a regular schedule, regardless of the share price. The investor purchases more shares when prices are low and fewer shares when prices are high. Dollar Cost Averaging (DCA) – Investopedia www.investopedia.com/terms/d/dollarcostaveraging.asp
(5) Higher returns are not guaranteed through this strategy. However, it is a sound strategy to help manage downside risk and can achieve improved outcomes as explained in the retirement distribution example in this report.
Important Disclosures:
¹This is a hypothetical example and is not representative of any specific investment. Your results may vary. (88-LPL)
Securities and advisory services are offered through LPL Financial, a registered investment advisor and broker-dealer, Member FINRA/SIPC.
Insurance products are offered through LPL or its licensed affiliates. Gatewood Wealth Solutions is not registered as a broker-dealer or investment advisor. Registered representatives of LPL offer products and services using Gatewood Wealth Solutions and may also be employees of Gatewood Wealth Solutions. These products and services are being offered through LPL or its affiliates, which are separate entities from, and not affiliates of, Gatewood Wealth Solutions.
Securities and insurance offered through LPL or its affiliates are:
- Not Insured by FDIC or Any Other Government Agency
- Not Bank Guaranteed
- Not Bank Deposits or Obligations
- May Lose Value
As Americans live longer, more adult children are stepping into a new and emotionally complex role: caregiver for aging parents. While this caregiving journey is often rooted in love and duty, it comes with significant financial, legal, and emotional challenges—many of which families are unprepared to navigate.
At Gatewood Wealth Solutions, we help families prepare for life’s key moments. Becoming a caregiver is one of those moments, and having the right plan in place can help you support your parents without jeopardizing your own financial well-being or confidence.
The Situation Many Couples Face
The typical scenario starts subtly. One parent begins needing help with errands, then medications, then transportation. Eventually, the need grows to include daily support—bathing, dressing, managing bills—or even full-time care.
For couples in their 40s, 50s, or 60s, this can be a difficult balancing act. They may still be working full-time, saving for retirement, or even supporting children in college. When caregiving duties grow, it creates stress, financial strain, and difficult decisions:
- Should one spouse reduce hours or leave work entirely?
- How do we pay for in-home care or assisted living?
- Are we prepared for the legal and medical decisions ahead?
- Will this derail our own retirement?
These are deeply personal—and deeply financial—questions.
Financial Considerations for Caregiving
Caring for a parent can quickly become a financial responsibility. Common costs include:
- Home modifications (ramps, walk-in tubs)
- In-home caregivers or visiting nurses
- Adult daycare programs or respite care
- Transportation services
- Medications, co-pays, or specialized therapies
- Long-term care or assisted living facilities
Medicare Vs. Medicaid: What They Cover (and what they don’t)
Medicare is health insurance primarily for those 65 and older. It covers hospital care, doctor visits, and short-term rehabilitation—but NOT long-term custodial care such as help with bathing, dressing, or eating.
Medicaid, on the other hand, is a needs-based program that can cover long-term care in a facility or at home—but only for individuals with very limited income and assets.
Coordination Between the Two:
In some cases, individuals can qualify for both Medicare and Medicaid (known as “dual eligibility”), but coordinating these benefits is complex and often requires professional guidance. Timing, asset structuring, and proper documentation are key to avoiding disqualification or delays in coverage.
Legal and Estate Planning Issues to Address
When you step into a caregiving role, you also step into a world of legal responsibilities. The following should be reviewed or created:
- Powers of Attorney (Financial & Medical): Ensure someone has legal authority to act on your parent’s behalf.
- Living Will/Advance Directive: Clarifies wishes regarding life-sustaining treatment.
- HIPAA Authorizations: Grants access to medical records.
- Updated Wills and Trusts: Review beneficiary designations, successor trustees, and asset titling.
- Asset Protection Planning: If long-term care may be needed, there are legal strategies to protect family assets within Medicaid’s lookback rules.
Gatewood can work alongside estate attorneys to help ensure the proper legal structures are in place and coordinate with elder law specialists when necessary.
Emotional and Lifestyle Strain
Many caregivers experience:
- Guilt over not doing enough
- Burnout from juggling work, children, and caregiving
- Conflict with siblings or spouses over roles and responsibilities
- Grief as they watch a parent’s health decline
We often remind families: you cannot pour from an empty cup. Planning ahead financially and legally can ease the stress and allow more energy for the emotional and relational aspects of caregiving.
Resources for Caregivers
You’re not alone in this journey. Here are a few reputable resources:
- Area Agencies on Aging (AAA): Local support and information services
n4a.org - Eldercare Locator: A free service to connect caregivers with local help
eldercare.acl.gov - Family Caregiver Alliance: Tools, education, and support groups
caregiver.org - Medicare.gov: Coverage information, providers, and cost estimators
www.medicare.gov - Medicaid Planning Resources: State-specific resources available through local elder law attorneys or planning professionals
How Gatewood Can Help
At Gatewood, we guide families through the complexities of caregiving—from financial planning to legal coordination to emotional support strategies. We:
- Model the impact of caregiving expenses on your own retirement plan
- Coordinate with estate attorneys and elder law professionals
- Identify insurance and long-term care funding options
- Help facilitate family conversations and clarify roles
- Help ensure planning stays aligned across generations
A Final Thought
You may never feel fully ready to become a caregiver—but with thoughtful preparation and the right support, you can approach it with confidence, clarity, and compassion.
If you’re facing—or anticipating—the responsibility of caring for an aging parent, let’s have a conversation. We’re here to help you prepare financially and emotionally for one of life’s most important roles.
Important Disclosures:
This material was created for educational and informational purposes only and is not intended as tax, legal or investment advice. For a comprehensive review of your personal situation, always consult with a tax or legal advisor. Neither LPL Financial nor any of its representatives may give legal or tax advice.
At Gatewood Wealth Solutions, we believe your cash should do more than just sit in a savings account. Whether you need short-term income or are planning for a future large expense, there are smart, managed strategies designed to keep your money working while staying aligned with your financial goals. That’s where our Cash Flow Advisory Strategy and Lump Sum Advisory Strategy come in.
What Are These Strategies?
Both strategies are actively managed cash and cash-equivalent allocations designed with a goal to help clients capture higher short-term yields while maintaining liquidity and stability. However, they serve two distinct purposes:
- Cash Flow Strategy is for ongoing income needs, such as monthly withdrawals in retirement or other recurring distributions.
- Lump Sum Strategy is for specific future expenses, such as a home down payment, tax payments, or a major purchase 6 to 24 months out.
How Do They Work?
Each strategy is structured using a tiered bucket system, with allocations managed by our Investment Committee. The funds are invested in a mix of ultra-short-term, high-quality bond funds and cash equivalents, allowing you to earn a competitive yield while keeping the risk low.
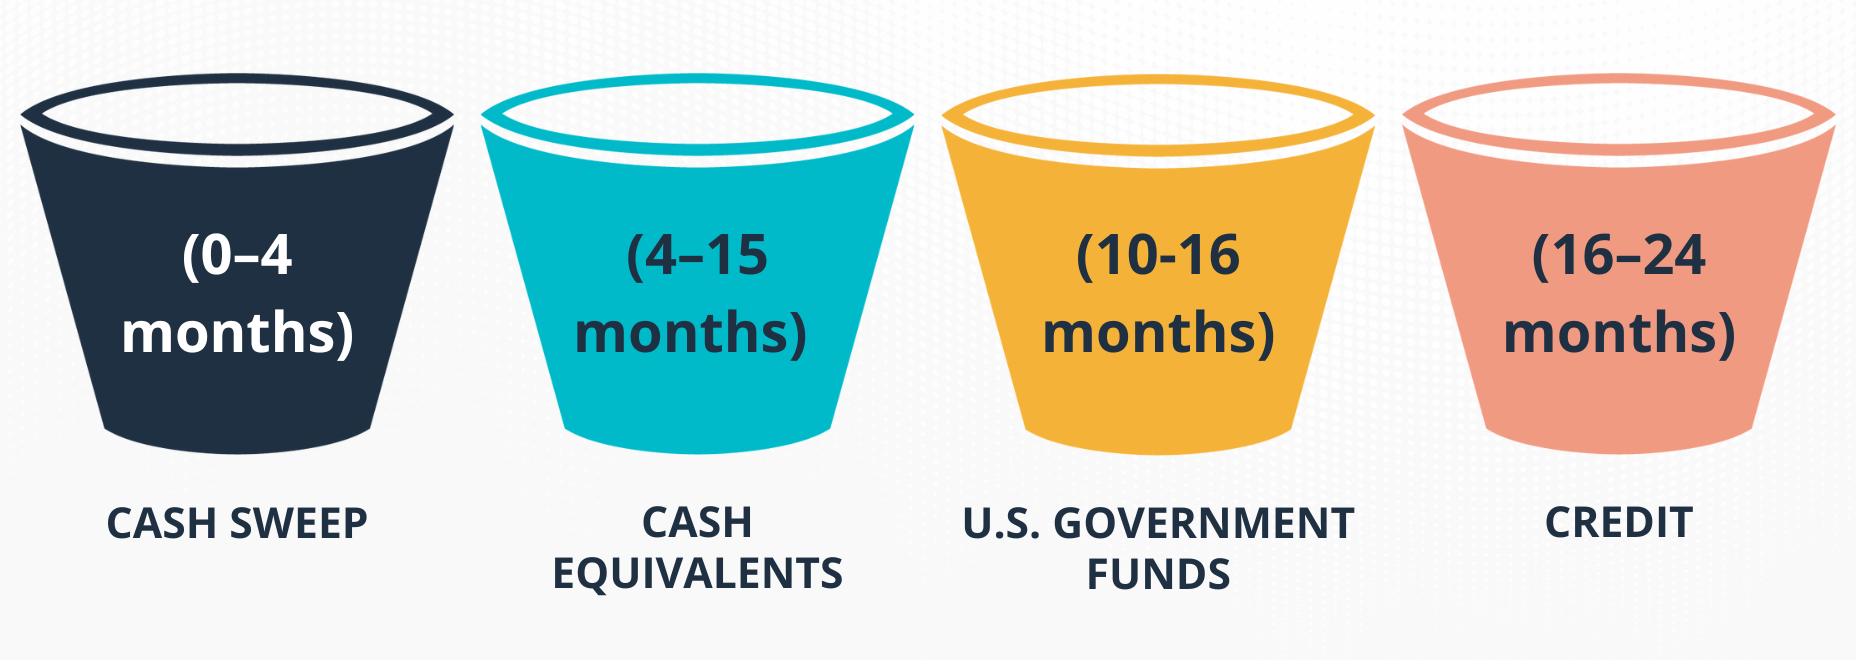
Both strategies use the same four investment buckets but are customized by time horizon and client-specific goals. Here is a breakdown of each bucket and its role within the strategies:
1. Cash Sweep (0–4 months)
- Purpose: Immediate liquidity
- Description: This bucket consists of FDIC-insured cash. It’s fully liquid and used for near-term distributions—typically covering 1 to 2 months of expenses in the Lump Sum Strategy and up to 4 months in the Cash Flow Strategy. This is your most accessible cash, designed to meet known, immediate needs.
- Why We Use It: It protects against the need to sell investments at an inopportune time and ensures quick access to funds.
2. Cash Equivalents (4–15 months)
- Purpose: Short-term stability with a yield advantage over traditional savings
- Description: This bucket is made up of high-quality, ultra-short-term bonds or money market funds with average maturities under 60 days. These investments aim to maintain a stable $1 value while earning a higher yield than FDIC-insured cash.
- Why We Use It: These instruments are low-risk and highly liquid, making them suitable for short-term needs while delivering higher interest income.
3. Government Duration (10–16 months)
- Purpose: Incremental return potential with modest volatility
- Description: This bucket contains U.S. government bonds with slightly longer maturities. These securities may have minor price fluctuations but offer a yield advantage when the interest rate outlook justifies extending duration.
- Why We Use It: When interest rates are expected to fall or stabilize, this bucket helps add return without taking on credit risk. We may hold this bucket selectively depending on the market environment.
4. Credit (16–24 months)
- Purpose: Higher return potential for mid-term needs
- Description: This bucket includes short-term corporate bonds. These offer higher yields than government securities but also carry credit risk. When credit spreads are attractive, this bucket adds value. When spreads are tight, as they are currently, we avoid this allocation.
- Why We Use It: When appropriately timed, it enhances returns without overextending risk. It is used only when the risk-reward tradeoff is favorable.
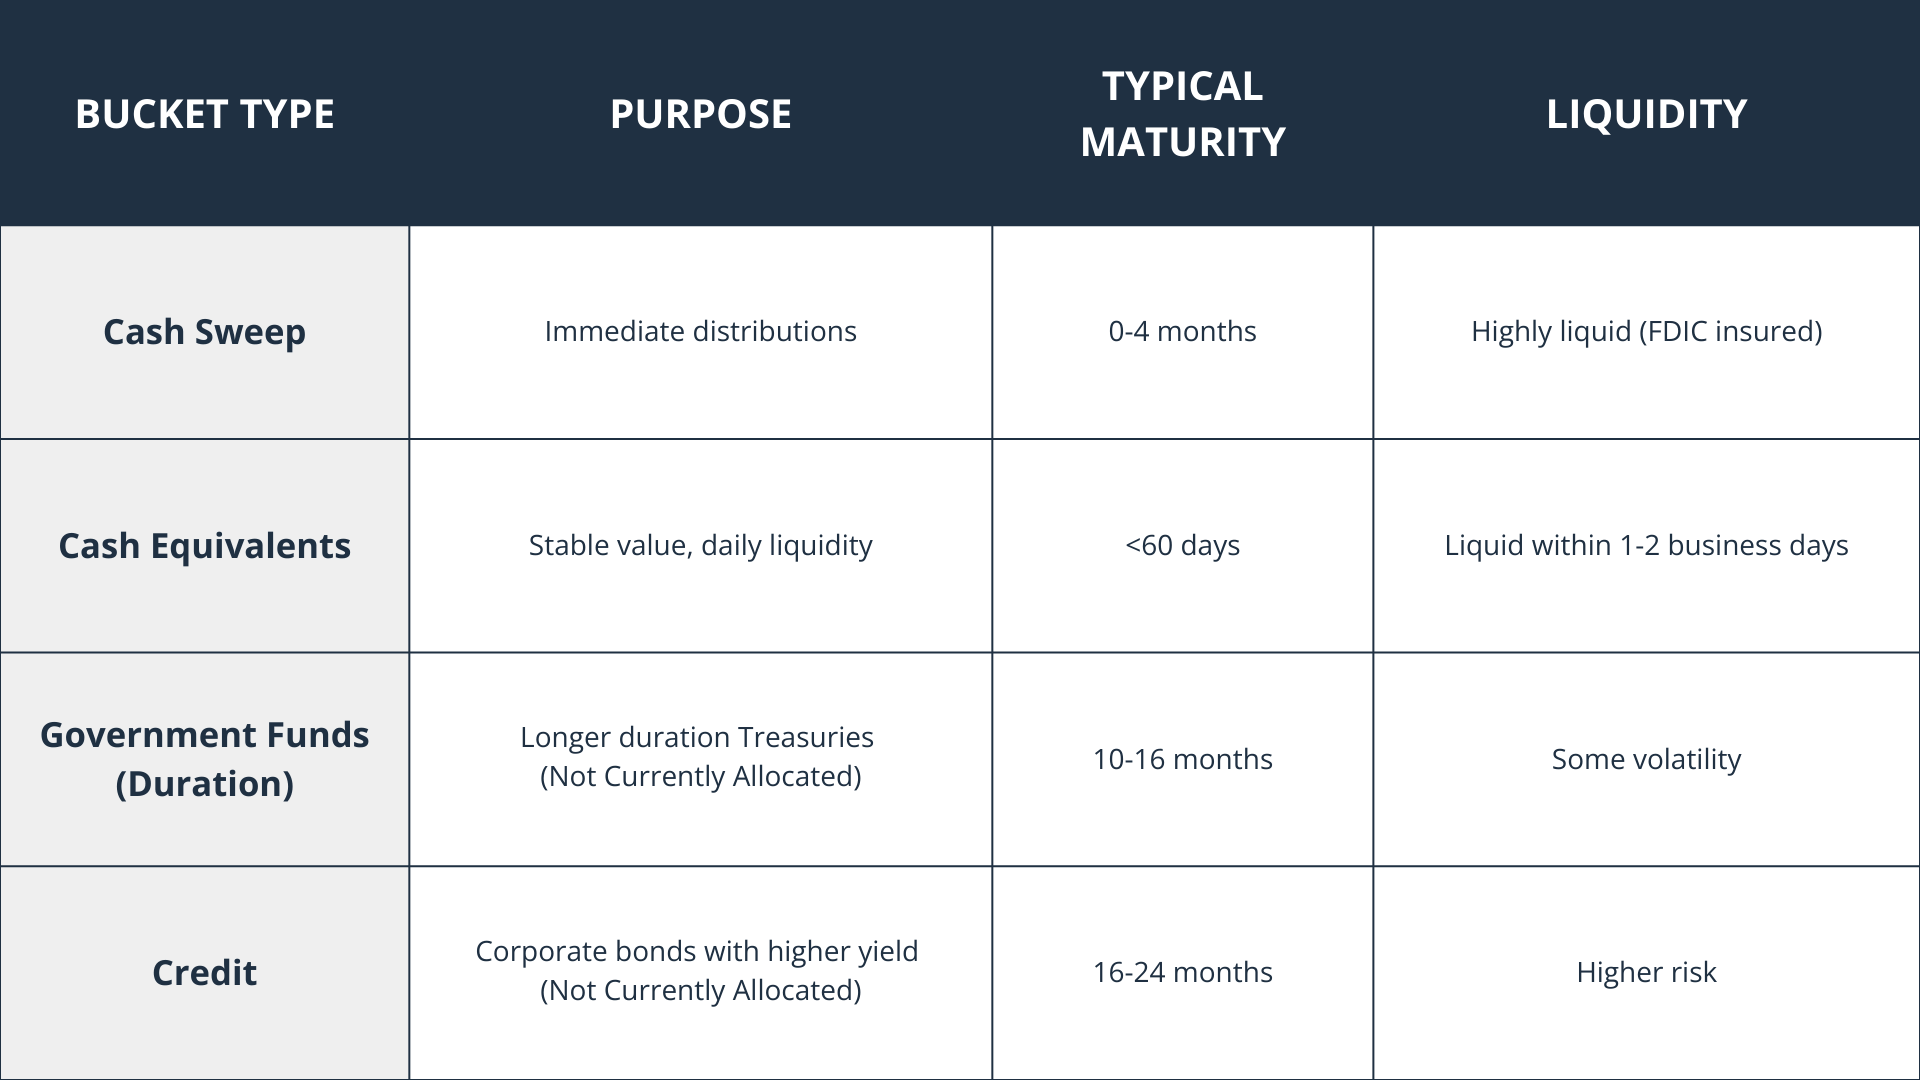
Here’s a simplified breakdown:
Making It Simple: A Helpful Analogy
To make the distinction even clearer, think of these two strategies like packing for a trip:
- The Cash Flow Strategy is your carry-on bag—it holds everything you need right away: monthly withdrawals, bills, and short-term expenses. It’s always close, easy to access, and organized to support your daily needs without touching your long-term investments.
- The Lump Sum Strategy is your checked luggage—it’s packed for something coming up later in the journey. Maybe it’s a major purchase, a home remodel, or another large one-time expense. You don’t need it today, but it needs to be ready when the time comes.
Both “bags” are thoughtfully packed to serve a specific purpose. By separating your short-term needs from your near-future plans, you avoid overloading your portfolio with cash—or worse, being forced to sell long-term investments at the wrong time.
When Is Each Strategy Appropriate?
- Use the Cash Flow Strategy if you:
- Are taking monthly or quarterly withdrawals
- Are in retirement and need predictable income
- Want to insulate your investment portfolio from market-driven withdrawals
- Use the Lump Sum Strategy if you:
- Have a known upcoming expense in 6–24 months
- Are saving for a home, wedding, remodel, or other large goal
- Don’t want to leave the money in a low-yield bank account but also don’t want the risk of the market
Cash Hub vs. Planning for the Future
The Cash Hub is part of our broader retirement income strategy. It represents a specific number of months’ worth of expenses we recommend keeping liquid to avoid selling long-term investments during downturns. For many retirees, we target 18 to 24 months of non-covered expenses in cash, creating a buffer for down markets.
The Lump Sum Strategy, on the other hand, is designed for one-time planned needs. Rather than letting those dollars sit idle in a checking account or risk losing value to inflation, we position the funds in a stable, managed solution.
Example: How a Client Might Use Both
Meet Sarah, age 62, recently retired. She has:
- $140,000 in cash from a recent bonus and stock option payout
- Monthly expenses of $10,000
- Social Security and a pension covering $6,000 per month
Her Plan:
- $96,000 goes to her Cash Flow Strategy (24 months of net cash needs: $10,000 – $6,000 = $4,000 × 24)
- $30,000 goes to her Lump Sum Strategy for a kitchen remodel in 18 months
- The rest stays in her investment portfolio for long-term growth potential
This allows Sarah to keep her distributions steady, avoid selling stocks in a downturn, and earn more on her near-term funds than she would at the bank.
Why Not Just Use a Savings Account or CD?
While savings accounts and CD’s offer less volatility, they fall short in three key areas:
- Low yields: Even high-yield savings accounts often return less than our managed strategies
- Inflexibility: CD’s lock your money for a set term, which may not align with your needs
- No strategy: Bank accounts are static. Our strategies are actively managed based on interest rates and your goals
That said, it’s important to note: unlike bank accounts, these funds must be sold before cash becomes available. However, the process is simple and only takes 1–2 business days to settle, and we handle the logistics for you.
Bottom Line: Purpose-Driven Cash Management
Your short-term cash shouldn’t be an afterthought. With thoughtful planning, strategic allocation, and active oversight, your money can stay accessible, and productive.
If you’re holding significant cash in the bank or unsure how to structure your liquidity, let’s talk about how these strategies can work for you.
Important Disclosures
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.
Investing involves risk including loss of principal. No strategy assures success or protects against loss
Government bonds and Treasury bills are guaranteed by the US government as to the timely payment of principal and interest and, if held to maturity, offer a fixed rate of return and fixed principal value.
CDs are FDIC insured to specific limits and offer a fixed rate of return if held to maturity, whereas investing in securities is subject to market risk including loss of principal.
An investment in the Money Market Fund is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency. Although the Fund seeks to preserve the value of your investment at $1.00 per share, it is possible to lose money by investing in the Fund.
This is a hypothetical example and is not representative of any specific situation. Your results will vary. The hypothetical rates of return used do not reflect the deduction of fees and charges inherent to investing
In today’s unpredictable world, having an emergency fund is not just a financial recommendation – it’s a necessity. The reality of unexpected expenses, whether they come from a medical emergency, sudden unemployment, or urgent home repairs, can create significant financial stress.
An emergency fund acts as a financial safety net, empowering you to manage these unforeseen costs without resorting to high-interest debt options like credit cards or loans.
Building an emergency fund requires a systematic approach, and here’s how you can do it in five practical steps:
1. Decide How Much to Save
The first step in creating an emergency fund is to determine the amount you need to save. A common guideline is to have enough to cover three to six months of living expenses. This figure should include rent, utilities, groceries, and any other regular expenses that would need to be paid even during a period of financial distress. To personalize your fund, consider your job security, the stability of your income, and any dependents who rely on your earnings.
2. Set Your Savings Target
Once you know how much you need to save, the next step is to set a realistic timeline for achieving this goal. Start by reviewing your budget to see how much you can comfortably set aside each month without compromising your daily financial health.
For some, this might be a modest amount, while others might be able to save more aggressively. The key is consistency; even small amounts can grow significantly over time due to the power of compound interest.
3. Choose Where to Keep Your Fund
The ideal location for your emergency fund is somewhere accessible but not too easily spent. High-yield savings accounts are a popular choice because they offer higher interest rates than regular savings accounts, helping your fund grow faster. These accounts also provide liquidity, allowing you to withdraw funds quickly and without penalties in case of an emergency.
4. Open Your Account
With a clear idea of where to keep your emergency fund, the next step is to open an account. Look for banks that offer competitive interest rates and low fees. Online banks often provide higher yields than traditional brick-and-mortar banks. Ensure that any account you choose is insured by the Federal Deposit Insurance Corporation (FDIC) or the National Credit Union Administration (NCUA) for added security.
5. Know When to Use the Fund
Finally, establish clear guidelines for when to use your emergency fund. It should only be used for true emergencies, such as unexpected medical expenses, crucial home repairs, or during a job loss – not for planned expenses or discretionary spending. After an emergency, focus on rebuilding the fund as soon as your financial situation stabilizes.
Financial Planning Matters
Building and maintaining an emergency fund is a fundamental aspect of a sound financial strategy. It provides not just financial confidence, but potentially may lead to less stress, knowing that you are prepared for life’s unexpected events. Start small, be consistent, and watch your safety net grow.
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.
This article was prepared by FMeX.
Money management and investment strategy are critical areas that deserve undivided attention, particularly for HENRYs – High Earners Not Rich Yet. This demographic often earns a significant income but has yet to amass substantial wealth due to various lifestyle choices or financial obligations. Moreover, they are usually in the early or middle stages of their careers, which leaves them vulnerable to market volatility and other uncertainties. Here, we outline eight vital tips for HENRYs on money management and investing in a volatile market.
Understand your financial situation.
The first step towards effective money management is understanding your financial status. Money management includes knowing your salary, savings, investments, debts, monthly expenses, and future financial responsibilities. Once you know your financial situation, you can work with a financial professional to create a plan responsive to changing market conditions.
Create an emergency fund.
An emergency fund is not just a financial safety net; it’s a source of security and peace of mind. It’s there to support you in case of job loss, medical emergencies, or unexpected expenses. Financial professionals recommend having at least three to six months’ worth of living expenses saved in an easily accessible account. This fund can provide you with confidence and financial stability, even during times of economic downturn or market volatility.
Manage debt.
Managing debt is a crucial aspect of financial responsibility for HENRYs. While they may have a significant income, it’s important to avoid accumulating debt without a clear plan for repayment. A high income doesn’t guarantee timely debt payment if it isn’t managed appropriately, which can lead to unnecessary financial stress.
Diversify investments.
One of the tried-and-true strategies for weathering a volatile market is diversification. Diversifying your investment portfolio across different asset classes, such as stocks, bonds, real estate, and commodities, can mitigate risk and improve returns. Diversification is not just about spreading your money across different investments; it should also consider geographical regions and sectors.
Manage risk.
Investing involves a certain level of risk. However, understanding and managing this risk is crucial, especially in volatile markets. To help manage risk, work with your financial professional to establish a risk tolerance level that helps guide your investment decisions. Always remember that high-risk investments can lead to high returns but can also result in substantial losses.
Another type of risk management to consider is having appropriate insurance coverage, such as property and casualty, liability, health, life, etc. Insurance coverage is imperative to protecting assets and avoiding premature liquidation if an unforeseen event occurs.
Keep a long-term perspective.
While short-term market fluctuations can be unnerving, HENRYs should maintain a long-term perspective as they work toward their goals. History has shown that markets tend to rebound over the long term, so emotion-driven reactions to market volatility can harm an investment portfolio.
Stay informed.
Staying informed about market trends, financial news, and economic indicators can help make informed financial decisions. Numerous online resources are available to learn more about personal finance and investing. Also, working with a financial professional can help HENRYs stay informed regarding how market volatility may impact their portfolio and goals.
Practice patience and discipline.
Finally, patience and discipline are pivotal in managing money and investing, particularly in a volatile market. It’s essential to stick to your long-term strategy and resist the temptation of short-term gains or panic selling.
In conclusion, HENRYs have a unique opportunity to accumulate wealth despite market volatility. By implementing these tips and working with a financial professional, HENRYs can navigate market volatility and set sail toward financial independence.
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual. To determine which investment(s) may be appropriate for you, consult your financial professional prior to investing.
There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio. Diversification does not protect against market risk.
Past performance is no guarantee of future results.
This article was prepared by Fresh Finance.
With summer on the horizon, many of us are eagerly awaiting exciting activities and well-deserved getaways. However, these adventures can also lead to higher expenses that put extra strain on our wallets. The key to enjoying a stress-free summer lies in effective budgeting. By planning ahead and managing your finances wisely, you can make the most of the season without breaking the bank.
Creating a summer budget
The easiest way to begin building your budget is by considering what expenses you already have planned, such as vacations, summer camps, or home improvements. You’ll want to factor in costs for travel, accommodation, transportation, dining out, entertainment, or any other activities you may be interested in. You can assign a specific dollar amount to each category, ensuring you account for both fixed and variable expenses.
Of course, the summer months may also bring several unexpected expenses, whether that’s surprise home or car repairs, spontaneous trips, or suddenly higher bills. So it’s always a good idea to leave extra wiggle room in your budget. Take these steps to help ensure you have the funds you need to cover all your costs this season.
Assess your financial situation
When creating a budget, first take a moment to review your income and savings. Be sure to consider all potential sources of income this summer, including your regular salary, possible bonuses, and any other side hustles you might have or could pick up. This will give you a better idea of what you can expect to bring in during the summer months and what you may be able to afford.
Besides your income, it’s also important to make note of your regular fixed monthly expenses such as rent or mortgage, utilities, and groceries. By subtracting them from your expected income, you can get an estimate of how much discretionary funds you’ll have available for summer activities, allowing you to create a more accurate budget.
After you have a good idea of your income and expenses, you can create goals for what you want to do this summer. Whether you dream of a tropical vacation, exploring local attractions, or simply enjoying quality time with loved ones, having a clear vision to guide your budgeting process will help you allocate funds to the areas that matter most to you.
After you’ve established your budget, you’ll need to work to keep to it by using these strategies throughout the season.
Before booking flights, hotels, or attraction tickets, it’s important that you thoroughly research and compare prices and look for deals, discounts, or early-bird specials. Doing so may take longer, but it could make a world of a difference by helping you save money and more comfortably afford what’s ahead. If you can discover a way to cut costs significantly in one area, you can then adjust your budget by shifting that money toward another summer-related expense.
Throughout the summer, take care to monitor your spending and check to see that you’re staying on budget. If you find that you’re deviating in a certain area, you can adapt accordingly and be more mindful about where and on what you’re spending your money. Utilize spreadsheets, online tools, or budgeting apps like Mint to simplify the process. By maintaining a detailed record, you’ll have a clear understanding of where your money is going and be able to make adjustments if necessary.
Because life is unpredictable, unexpected expenses may arise during the summer, so it’s essential to be flexible with your budget when you need to. Consider building an emergency fund you can use to handle unexpected costs, and prepare ways you can shift your budget as needed without derailing your overall financial goals.
While it’s always better to save in advance, it’s never too late to begin budgeting for your upcoming expenses. By taking this step now, you can better ensure that you have a fun-filled, stress-free season spent doing the things that you love.
This article was prepared by ReminderMedia.
At Gatewood Wealth Solutions, we prioritize empowering our clients with robust financial strategies, including effective cash management to weather market uncertainties. Understanding the importance of maintaining liquidity during bear markets while remaining confidently invested for the long-term, we review and update cash needs regularly. Here’s how we determine appropriate emergency reserves tailored to different life stages using our Gatewood Rules-of-Thumb:
Cash Management: Pursuing Stability During Market Fluctuations
The primary strategy is to maintain sufficient cash reserves for liquidity needs, especially during bear markets. By holding targeted cash reserves during one’s financial journey, individuals can mitigate the risk of selling investments during down markets and remain confidently invested for the long-term.
Determining Emergency Cash Reserves by Life Stage
Emergency reserve targets are based upon an individual’s life phase and total monthly expenses.
We follow the Gatewood Rules-of-Thumb below for the number on months’ worth of total household expenses one should keep in cash:
- Life Phase 1 – Early-Career Accumulation (3-6)
- Life Phase 2 – Mid-Career Accumulation (6-18)
- Life Phase 3 – Late-Career Nearing Retirement (12-24)
- Life Phase 4 – Retirement Income Distribution (18 – 30)
We then determine one’s near-term lump sum expense needs. These include significant financial commitments, such as making a down payment on a new house, buying a new car, funding a home renovation project, or covering tuition fees for a child’s education.
Calculating the Cash Total Target
To determine the total cash target, we assess:
Emergency Reserves (3-30 Months’ Expenses – Life Phase Based)
+ Near-Term Lump Sum Expense Need (0-24 Months from Now)
= TOTAL CASH TARGET
Conclusion
By targeting emergency cash reserves according to your life stage and financial needs, we aim to provide investor confidence during economic uncertainties. Contact Gatewood Wealth Solutions today to explore how we can tailor a cash management plan to align with your specific financial goals and aspirations.
Important Disclosures:
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.
A personal credit crisis is something many people fear, as it can lead to financial ruin and burden an individual with immense debt. Fortunately, steps can be taken to avoid such a crisis, even for high earners who may seem financially secure. When managed poorly, credit can invite various potential issues, including problems with enforceable legal judgments, fraud, overspending, and negative impacts on your credit score. Here are ten ways high earners can strategically manage their finances.
1. Budget and track expenditures
It’s essential to maintain a strict budget irrespective of the size of one’s income. Uncontrolled spending can lead to incurring a significant amount of debt, which in turn can trigger a credit crisis. High earners should always keep a detailed record of their expenditures to prevent overspending and stay within their budget.
2. Diversify income streams
While high earners may seem financially secure, relying on a single source of income can be risky. Diversifying income streams is an effective way to help address financial stability and mitigate a credit crisis by using credit when funds are scarce. If appropriate, consider passive income sources like real estate, stocks, or bonds.
3. Conduct regular financial audits
High earners must regularly audit their financial health to check uncontrolled spending, investment performances, and wealth accumulation. High earners must also periodically audit their credit reports to detect any errors or anomalies that could negatively affect their credit scores. In case of discrepancies, it’s crucial to initiate a dispute promptly to preserve a favorable credit status.
Another aspect of financial audits is monitoring interest rates, which impact the interest rate on credit cards, revolving lines of credit, and some loans that high-earners may carry. The higher the interest rate, the more the credit will cost over time.
4. Avoid unnecessary debts
Due to the vast credit card limits that high earners enjoy, using credit cards responsibly is essential. The higher the balance on a credit card, the more adverse the effect on a credit score.
High earners should avoid taking on unnecessary debts, which can lead to financial instability and potentially trigger a credit crisis. Avoid debts incurred through credit cards, unsecured loans, and high-risk investments.
5. Maintain an emergency fund
An emergency fund can be a safety net to cover unexpected expenses. Emergency funds provide a financial buffer that prevents the need to take on high-interest short-term debt, which could lead to a potential credit crisis.
6. Stay insured
Maintaining appropriate insurance policies to protect against unforeseen circumstances that may cause financial hardship is crucial. These include health insurance, disability insurance, liability insurance, property and casualty insurance, and long-term care insurance to protect assets against unforeseen legal judgments or collections.
7. Engage in Financial Education
High earners should continuously educate themselves about personal finance, investment strategies, tax laws, and other relevant topics to make informed financial decisions and prevent financial mishaps that could lead to a credit crisis.
8. Hire a financial professional
A financial professional can provide professional guidance on managing wealth and debt, tax planning, retirement planning, and other financial aspects. They will provide valuable advice and strategies to help high-earners work toward their goals while addressing credit issues.
9. Protect against fraud
Due to their wealth, high earners can be attractive targets for scammers. Therefore, preventing fraud by regularly checking credit reports, safeguarding personal information, and setting up fraud alerts on credit and bank accounts is crucial.
10. Save for retirement
High earnings do not guarantee a financially confident retirement. Therefore, it is essential that high-earners consistently save and invest for retirement, regardless of their current income level. Without financial confidence, high-earners may resort to credit use during retirement, which could lead to financial insecurity later in life.
Financial independence for high earners is about earning a high income and managing it responsibly. These preventive measures can help high earners manage their wealth and credit, maintain a positive credit score, and help mitigate a credit crisis.
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.
This article was prepared by Fresh Finance
Financial responsibility isn’t always easy to learn, but it’s an essential part of taking control of your finances and using your income to its fullest. This responsibility can lead to better spending tendencies that can, in turn, help you pay off your debts faster and build up savings to protect you in the future. So if you’ve struggled to stay on top of your spending, here are a few key ways you can adjust your habits and mindset to better meet your financial goals.
Create and stick to a realistic budget
Budgeting is a great first step toward managing your finances. In fact, according to a survey conducted by the Certified Financial Planner Board, people who budget feel more financially secure and confident than those who don’t. When you budget, you’re being strategic with your spending and controlling where your money goes each month. Budgeting strategies like the 50/30/20 method—where 50 percent of your income goes toward necessary living expenses, 30 percent is spent on your additional wants like eating out and entertainment, and 20 percent is put directly into savings—can help you create a realistic budget and become more financially responsible and secure.
Keep all your monthly expenses in one place
It’s essential to know what bills you must pay each month and when they’re due since missing one can hurt your credit score and end up costing you more money. It’s a good idea to have a spreadsheet that lists all your recurring expenses and their due dates. If spreadsheets aren’t your thing, you can instead use an app like Mint or even just make a note on your phone to better track your recurring expenses. It’s also important to automate your payments so you won’t have to actively think about them. Whatever method you opt for, tracking bills and expenses can help you keep up with your spending and give you an idea of how much will be coming out of your account and when.
Start giving yourself a weekly allowance
Many people receive an allowance growing up, but this tends to stop when you’re an adult and start earning a paycheck. However, setting up a weekly spending allowance for yourself can help you cut back on excess spending. You can set aside cash for each week or simply have a set number in mind to put on your debit or credit card. Either way, an allowance shows you how much money to dedicate to lunches, coffee, home goods, and anything else that you might want to buy in a given week. Having a specific number helps you to say no to that extra dinner out and instead save money by making something at home.
Consider saving as a payment to yourself
Setting aside a specific portion of your income each month can help you save for an upcoming trip, additional spending during the holidays, or emergency expenses. Putting money directly into your savings can give you a sense of security, so look at it as a payment to your future self. You’re preventing potential headaches down the road when it comes time to spend extra money on something, and you’ll be grateful that you had the forethought to put money away when you did.
Plan for larger purchases
Before making an expensive purchase, be it for a new piece of furniture or a nice outfit, it’s important to think it through. You don’t want to make a rash decision, especially if the item far exceeds what you’re used to spending. Give yourself some time to consider the purchase and plan out how you’re going to save for it. You can set aside money every paycheck for the item, allocate funds outside of your usual savings, or, if you’re dipping into your savings, check to make sure the purchase won’t bring the total amount too low for comfort. Taking control of your spending is about being strategic with your purchases and giving big expenses more consideration than you may have in the past.
Pay off your credit cards every month
Credit cards can be a great financial tool to have, but paying off the full balance every month is an important part of being more financially responsible. Just as important, they often have high interest rates that can significantly increase your debt if you don’t pay the entire balance—so it’s important to manage them the best you can. If you find that you can’t pay the full amount each month, consider adjusting your spending habits. Instead of picking up coffee every morning, eating all your lunches out, or adding a new item to your virtual cart every day, you can save money by making your own coffee and lunches and cutting back on your online shopping. These expenses may not seem like a lot in the moment, but they can quickly add up and create a high monthly balance that isn’t always easy to pay in full.
Regularly review your spending
To make sure that you’re continuing to stay on top of your finances, you want to regularly review your spending. Look at your credit card statements and your savings and checking accounts, and see what you are spending your income on each month. Carefully reviewing your accounts can help you better understand your financial habits and see where perhaps you’re spending too much and need to cut back. It’s simply a way to hold yourself accountable, allowing you to adjust your spending accordingly.
By taking a few easy steps to better control your spending, you can manage your finances and become more financially secure.
This article was prepared by ReminderMedia.

